 Property
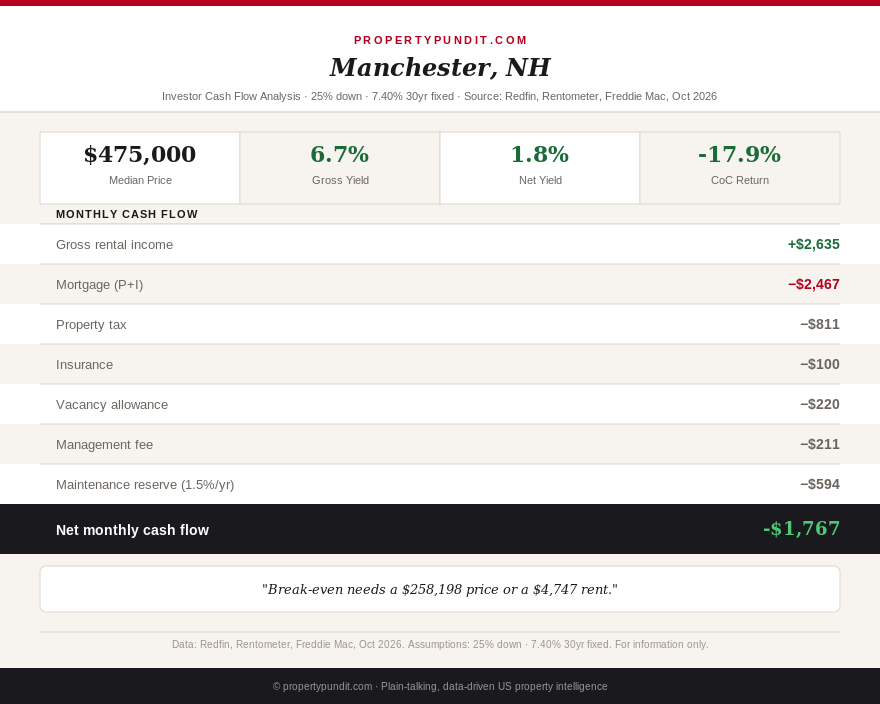
You've seen the pitch: no wage tax, no sales tax, some of the cheapest homeowners insurance in the country, and a state where prices keep setting records. Now you want to know whether a New Hampshire rental finally works at today's mortgage rates. At the Freddie Mac rate of 7.40% (October 15, 2026), the median Manchester house ($475,000, Redfin, three months ending August 2026) loses $1,767 a month as a rental on a 25% down payment. In August this site published -$1,114 for the same city.
The price that works in Manchester is near $258,000, about 46% below the median. Nashua loses more, about $2,575 a month, and Coos County, the cheapest in the state, gets close to break-even only if you believe a rent figure I couldn't pin down. New Hampshire's tax advantages are real, but they only pay when a property earns something to tax.
This is the third New Hampshire pass of the year. The method matches the recent state passes: 25% down, a 30-year fixed at 7.40%, a 2.05% effective property tax rate, a $100 monthly insurance estimate, 8% management, one month of vacancy a year and a 1.5% annual maintenance reserve.
Get this in your inbox every Friday.
One email. The number that matters and what it means for you.
New Hampshire cash flow at 7.40%, market by market
| Market | Price | Rent | Full payment | Net cash flow | Coverage | Break-even rent | Break-even price |
|---|---|---|---|---|---|---|---|
| Manchester | $475,000 | $2,635 | $3,378 | -$1,767 | 0.78 | $4,747 | $258,198 |
| Nashua | $550,000 | $2,400 | $3,896 | -$2,575 | 0.62 | $5,478 | $234,076 |
| Coos County | $224,500 | $1,702 | $1,649 | -$506 | 1.03 | $2,307 | $162,431 |
Prices are a Redfin median for Manchester ($475,000, three months ending August 2026, up 3.3% year over year) and New Hampshire Association of Realtors single-family medians for Nashua ($550,000, down 0.5%) and Coos County ($224,500), all for September 2026. Rents are Rentometer three-bedroom averages for Manchester ($2,635) and Nashua ($2,400), both dated October 18, 2026 and covering all property types, plus a HUD three-bedroom fair market rent reading for Coos County. "Full payment" means principal, interest, property tax and insurance; "coverage" is rent divided by that payment. Many DSCR lenders look for 1.0 or better, so Manchester and Nashua would struggle at underwriting as well as in your bank account. For how those loans work, see the DSCR loan guide.
So what for you: if your plan needs a rental to pay its own way, neither Manchester nor Nashua can do it at 7.40%, and the Coos result depends on a rent number you should verify before you rely on it.
Why August's -$1,114 became -$1,767 in Manchester
Most of the damage is bookkeeping, not the market. The August pass used a 5% vacancy allowance and no repair reserve. Today's method charges a full month of vacancy and a 1.5% annual maintenance reserve, which is $594 a month on a $475,000 house.
| Step | Manchester net per month | What changed |
|---|---|---|
| August pass, recalculated | -$1,124 | 6.69% rate, $462,000, $2,298 rent, 5% vacancy, no reserve |
| Today's method, same inputs | -$1,778 | One month of vacancy plus the $578 reserve on $462,000 (-$654) |
| Rate rises to 7.40% | -$1,943 | Payment up $165 |
| Price rises to $475,000 | -$2,049 | Redfin median up $13,000 (-$106) |
| Rent rises to $2,635 | -$1,767 | Rentometer three-bedroom average replaces the Zumper figure (+$282) |
The August article printed -$1,114; recalculating it today gives -$1,124, a $10 rounding difference. The rate move cost about $165 a month, which is the part you can blame on the Fed and the 10-year Treasury. The rent input did the opposite and recovered $282, but it comes from a source that averages apartments and houses together, so it may be generous for a single-family rental. Freddie Mac's rate was 6.69% on the August date and is 7.40% now, a 71 basis point rise (the August New Hampshire article has the earlier inputs).
So what for you: any New Hampshire number published before this fall, including ours, probably overstated the cash flow, so rerun your own inputs with a full vacancy month and a repair line before you trust them.
Coos County: the cheapest sticker price and a rent nobody can pin down
Coos County's median single-family price was $225,000 in August, down 18.2% from a year earlier on only 46 closed sales (New Hampshire Association of Realtors via Bean Group, September 2026), and $224,500 in September (New Hampshire Association of Realtors via Nashua Ink Link, October 11, 2026). In May the same county was $269,900 in the August pass. A median on 46 sales swings with the mix of houses that happen to close.
The rent is the harder problem. The HUD fair market rent table published by New Hampshire Housing for fiscal year 2026 gave me $1,287 for two bedrooms and $1,702 for three bedrooms in Coos County. The August pass used $1,275 for three bedrooms. At $1,702 the house nets -$506 a month with coverage of 1.03. At $1,287 it nets -$853 and coverage falls to 0.78. The break-even rent is $2,307 either way, so even the best case needs about 36% more rent than the highest figure I found.
So what for you: Coos County is the only place in this set where the numbers come close, but a falling price on thin sales and an unconfirmed rent are a poor foundation for a $168,000 loan.
Does appreciation cover the carry?
An investor can lose money monthly and still win if the price climbs, so test it. Take the yearly cash loss, subtract the first-year principal you pay down, and divide by the purchase price. That's the annual price growth you need just to break even before selling costs and taxes.
| Market | Yearly cash loss | Year-one principal | Growth needed | Recent price change |
|---|---|---|---|---|
| Manchester | $21,204 | $3,349 | 3.8% | +3.3% (Redfin, August 2026) |
| Nashua | $30,900 | $3,878 | 4.9% | -0.5% (NHAR, September 2026) |
| Coos County | $6,072 | $1,583 | 2.0% | -18.2% (NHAR, August 2026) |
Manchester comes close: it needs 3.8% a year and has been rising 3.3%. Statewide the picture looks better, with the September single-family median at $569,900 versus $535,000 a year earlier, up 6.5% (New Hampshire Association of Realtors via Nashua Ink Link, October 11, 2026). But that gain is driven by lake and ski counties. Belknap County rose 20.3% and Strafford 12.5% in August, while Hillsborough County, which includes Manchester and Nashua, fell 3.2% (Bean Group, September 2026).
So what for you: buying Manchester is a bet that the city keeps rising at least as fast as it has, and Nashua and Coos are not rising at all right now.
Supply is tight, so don't count on a bargain
New Hampshire still has 2.9 months of supply as of September, up from 2.6 a year earlier, and anything under four months favors sellers (New Hampshire Association of Realtors via Nashua Ink Link, October 11, 2026). In August, statewide inventory reached 3,055 single-family homes, up 18.7% year over year, and the median home spent 27 days on the market (Bean Group, September 2026). In Manchester, homes sold in a median of 22 days at 101.7% of list price, and 62.3% sold above list (Redfin, three months ending August 2026). Price drops are rising there too: 23.9% of listings, up 4.0 points.
The affordability side explains why. The association's index says median income covers just 51% of the monthly payment, tax and insurance on the median home, down from 58 a year earlier, and a quarter-point rate rise adds about $100 a month to a $569,900 purchase with 20% down. Buyers are stretched, which should cap price growth, but sellers still hold the cards because there are so few homes.
So what for you: getting Manchester down to $258,000 would require a 46% discount that a market selling at 101.7% of list is not offering, so plan around the price and rent you can actually get.
The tax pitch, again
New Hampshire has no tax on wages and none on individual capital gains, and the interest and dividends tax was fully phased out in 2025. The part that gets left out of the sales pitch is the 7.7% Business Profits Tax on net business profits above $50,000, which can reach a rental held in an LLC (the usual structure for a DSCR loan, per the New Hampshire Department of Revenue Administration and the August pass). All three properties here lose money, so there is no profit to tax. The same lesson applies as in Nevada: a tax advantage only pays when the property earns something to tax.
Property tax is the line that matters. I used 2.05%, the 2026 rental effective rate from Steadily, for every market. Nashua's actual 2025 rate is $16.83 per $1,000 of assessed value (New Hampshire Department of Revenue Administration via Nashua Ink Link, November 10, 2025), which is 1.683% if your house is assessed at full market value. At that rate Nashua's loss shrinks by $168 a month to about -$2,407, and Manchester's would be about -$1,622 at the same rate. I couldn't confirm Manchester's current rate or any assessment ratios, so check the town's figure for your parcel.
So what for you: before you buy anywhere in New Hampshire, get the town's tax rate and last revaluation date, because the difference between 1.68% and 2.05% is worth about $150 a month on a $475,000 house.
What this means for you
Skip Manchester and Nashua as cash-flow purchases at 7.40%. If your thesis is appreciation, Manchester has a case only if it keeps rising near 4% a year, and you'd be paying about $21,000 a year to wait. If you already own a New Hampshire rental, this is the week to rerun your numbers at today's rate and with a repair reserve.
If you still want New Hampshire, three moves make it less costly. Put at least 30% down or seek a seller credit toward a rate buydown, since every quarter point is worth roughly $78 a month in principal and interest on a $356,000 loan. Look at a duplex rather than a single-family house, because two rents against one tax bill is the only structure that came close in the Wichita duplex comparison. And compare with a market where the rent-to-price ratio is higher, such as Nebraska, where a $175,000 Omaha house nets -$7 a month at the same rate.
What I couldn't verify
Several inputs are carried, scaled or dated. Insurance at $100 a month is the 2026 Insurify and LendingTree range ($96 to $101) carried from the August pass, not a landlord policy quote for these houses, and landlord coverage usually costs more. The 2.05% tax rate is a statewide rental average, not a parcel bill. Rentometer's averages combine apartments and houses and don't state a sample size. The Coos County rent comes from my reading of a fair market rent table, and I got two different numbers for the bedroom counts, so treat the $1,702 as the optimistic case. Redfin's Manchester page also showed a different headline price ($460,000, down 5.9%) in its meta description than in its body ($475,000), and I used the body. I didn't find a Concord or Dover current median, a Manchester house-only rent comp, or a parcel-level assessor figure.
Frequently asked questions
Is New Hampshire a good place to buy a rental property at 7.40% mortgage rates?
Not for cash flow. At 7.40%, the median Manchester house ($475,000) rented at $2,635 loses about $1,767 a month on 25% down after 8% management, one month of vacancy and a 1.5% maintenance reserve. The case for New Hampshire rests on appreciation, and Hillsborough County's median fell 3.2% in August.
What rent does a Manchester house need to break even at 7.40%?
About $4,747 a month on a $475,000 purchase with 25% down. That's 80% above the $2,635 rent used here and 94% above the $2,442 HUD fair market rent for a three-bedroom in the Manchester metro area.
Does New Hampshire's lack of income tax help real estate investors?
Only if the rental earns a profit. New Hampshire has no wage or individual capital gains tax, but a rental held in an LLC can owe the 7.7% Business Profits Tax on net profit above $50,000. The properties tested here all lose money at 7.40%, so the income tax advantage is worth nothing right now.
Why did the Manchester rental math get worse since August?
The method now includes a 1.5% maintenance reserve and a full month of vacancy (-$654 a month), the rate rose from 6.69% to 7.40% (-$165), and a $13,000 higher price cost another $106. A higher rent estimate recovered $282. August's published figure was -$1,114; the same market is -$1,767 today.