 Property
You liked the August Memphis numbers enough to keep the tab open: a debt service coverage ratio of 1.24, a lender who would say yes, and a monthly shortfall of only $115. Then the weekly 30-year rate went from 6.66% to 7.24%, a 0.58-point jump, and the same house now sits at 1.19 and loses $163 a month. That is the third time this series has run Tennessee, and the first time the biggest question isn't the rate. It's which Memphis price you believe.
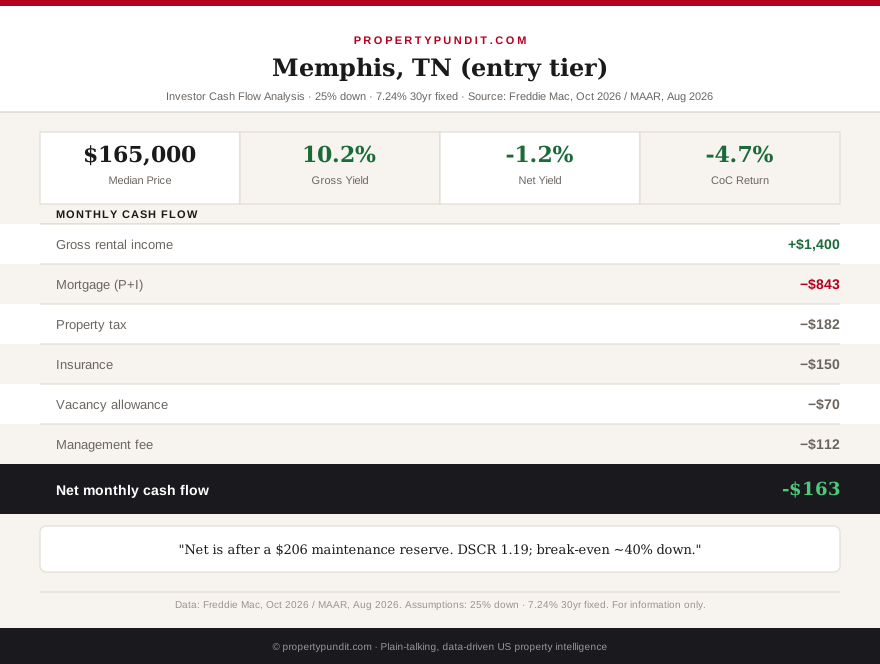
One rate move turned a 1.24 into a 1.19
Here's the Memphis entry-tier rental from our August Tennessee spotlight, re-run at Freddie Mac's October 29 average of 7.24% (up from 6.66% on August 27). Everything else is unchanged: a $165,000 purchase, 25% down, a 3-bedroom rent of $1,400, the in-city Memphis tax rate of 1.32% and $150 a month of insurance.
| Item (monthly) | Aug. 27 at 6.66% | Oct. 29 at 7.24% |
|---|---|---|
| Principal and interest ($123,750 loan) | $795 | $843 |
| Property tax (1.32%) | $182 | $182 |
| Insurance | $150 | $150 |
| Total payment (PITIA) | $1,127 | $1,175 |
| Gross rent | $1,400 | $1,400 |
| DSCR (rent divided by PITIA) | 1.24 | 1.19 |
| Vacancy (5%), management (8%), maintenance (1.5% a year) | -$388 | -$388 |
| Cash flow after operating costs | -$115 | -$163 |
The rate cost you $48 a month, and it cost the deal its cushion. Many DSCR lenders look for a ratio of 1.20 or better even when their written minimum is 1.0, so 1.19 is the difference between a routine approval and a pricing conversation. Our DSCR loan guide explains how that ratio feeds into your rate and required down payment.
So if you underwrote Memphis in August and haven't re-run it, assume your lender's cushion is thinner and your monthly loss is about $50 deeper than you planned.
Memphis is $152,000 or $230,000, depending on who counts
Two credible sources disagree on what a Memphis house costs, and the gap decides whether the deal is thin or hopeless. Zillow lists a typical Memphis home value of $151,794 for September 2026 (Zillow home values page). The Memphis Area Association of Realtors reports a median price of $230,000 for existing homes closed in August 2026, up 9.5% from $210,000 a year earlier, and $238,175 across all sales including new construction, up 5.9% (Memphis Area Association of Realtors, August 2026 report).
They diverge for real reasons. Zillow's index estimates the value of every home in the city, including the many older, low-priced houses that rarely trade. The Realtors' report counts recorded deeds across Shelby, Fayette and Tipton counties, which pulls in suburban sales that sit well above city levels. Bank-owned sales in that report had a median of just $82,500 on 16 deals, which shows how far down the cheap tail runs.
| Price source | Price | Rent assumed | PITIA | DSCR | Cash flow |
|---|---|---|---|---|---|
| Zillow typical value, Sept. 2026 | $151,794 | $1,294 | $1,093 | 1.18 | -$157 |
| Entry tier from August spotlight | $165,000 | $1,400 | $1,175 | 1.19 | -$163 |
| Realtors existing-home median, Aug. 2026 | $230,000 | $1,450 | $1,579 | 0.92 | -$605 |
All three use 25% down, 7.24%, the 1.32% in-city tax rate, $150 insurance and the same 13% vacancy-and-management deduction plus a 1.5% annual maintenance reserve. The rents are our carried assumptions: $1,294 is the low end of the June 3-bedroom range from Rentometer, RentHop and Zillow, $1,400 is the midpoint we used in August, and $1,450 is the August figure for a median-priced house. None was refreshed for this pass.
The $152,000 houses probably need more than a 1.5% maintenance reserve, and the $230,000 houses lose more than $600 a month, so for you the cheap end of Memphis is the only part of the market worth modeling.
What it takes to break even on a $165,000 Memphis house
Change one input at a time and hold the rest. Here is what each lever has to reach before the monthly cash flow hits zero on the entry-tier house.
| Lever (one at a time) | Needed for $0 a month | Today |
|---|---|---|
| Down payment | About 40% ($66,000) | 25% ($41,250) |
| Mortgage rate | About 5.20% | 7.24% |
| Purchase price | About $143,000 | $165,000 |
| Monthly rent | About $1,588 | $1,400 |
Rent and price levers are within 13% of today's figures, which is the encouraging part. The rate lever is the discouraging one: even a 3% mortgage only gets this house to +$159 a month. Insurance moves the result too. At $100 a month the loss is $113; at $250 it grows to $263. The rent range from the June sources, $1,294 to $1,436, brackets the loss between $132 and $255.
The cleanest route to a break-even Memphis rental right now is more cash down, since a 40% down payment lands near zero and 50% down earns about $118 a month, and if that's more equity than you want parked in one house, the math points toward waiting.
Nashville and Knoxville: the gap is wider
Nashville's median sale price was $480,000 in July, up 1.1% from a year earlier but below June's record of $495,000, according to RE/MAX data reported by WSMV. Active inventory rose 10% to 12,461 homes and the average sale took about 40 days (RE/MAX via WSMV and Houwzer, July 2026). Our Nashville versus Memphis comparison compared the two cities head to head earlier this year.
| Market | Price | Rent | PITIA | DSCR | Cash flow | Break-even price |
|---|---|---|---|---|---|---|
| Memphis entry tier | $165,000 | $1,400 | $1,175 | 1.19 | -$163 | $143,000 |
| Knoxville (carried from Aug.) | $325,000 | $1,700 | $2,028 | 0.84 | -$955 | $191,000 |
| Nashville (RE/MAX, July) | $480,000 | $1,950 | $2,966 | 0.66 | -$1,870 | $214,000 |
Nashville now loses $1,870 a month, up from $1,731 in August, and would need to cost about $214,000 to break even, 55% below its median. Knoxville's price and rent are carried from the August pass (Redfin three-month median through July and Zillow rent near $1,731 in January), so treat its $955 loss as an estimate. Even with no mortgage at all, Nashville nets only about $584 a month after tax, insurance, vacancy, management and maintenance, a weak return on $480,000 of cash.
That means if your plan involves financed cash flow in Nashville or Knoxville at 7.24%, the plan is really an appreciation bet, and you should price it as one.
The call on Tennessee at 7.24%
Frankly, the math points toward one of two moves. Either buy the cheapest sound Memphis stock with about 40% down and accept a near-zero, low-risk hold, or keep your cash and wait for rates near 5.2% or a price near $143,000 on the same house. Most people who run these numbers end up discovering that the lender test and the bank-account test have drifted apart again, and the second one is the one that pays the bills. Tennessee's no-income-tax, landlord-friendly rules still help, but they can't fix a 7.24% rate on a $1,400 rent.
For a county-level view of where yields still clear this bar, our single-family rental yield map is the better starting point than any Tennessee metro right now.
Get this in your inbox every Friday.
One email. The number that matters and what it means for you.
Frequently asked questions
Is Memphis still a good place to buy a rental property in 2026? It's the only major Tennessee market where the numbers come close. At 7.24% with 25% down, a $165,000 house renting for $1,400 passes a typical DSCR test at 1.19 but loses about $163 a month after vacancy, management and maintenance.
What is the median home price in Memphis? It depends on the source. Zillow lists a typical home value of $151,794 (September 2026), while the Memphis Area Association of Realtors reports an August 2026 median of $230,000 for existing homes and $238,175 for all sales.
Does Tennessee have a state income tax? No. Tennessee repealed its Hall income tax on investment income effective January 1, 2021. Property tax is set locally, and an investor buying inside Memphis city limits pays about 1.32% of market value.
How much down payment does a Memphis rental need to break even? About 40% on a $165,000 house at 7.24%, or $66,000, assuming $1,400 rent, 1.32% property tax and $150 monthly insurance.