 Property
You underwrote Spring Lake in August, saw $17 a month of cushion and told yourself that was thin but real. Since then the 30-year rate has climbed from 6.67% to 7.32%, and the same $210,000 rental that squeaked past break-even now loses $52 a month. If you're an investor sitting on a North Carolina deal that "pencils" on last quarter's rate, this is the pass that tells you whether it still does.
The short answer: Charlotte and Raleigh don't come close, and Spring Lake has crossed from a rounding-error profit to a rounding-error loss. Freddie Mac's weekly average was 7.32% on October 22, 2026, the first decline in nine weeks but still 1.13 points above a year ago (Freddie Mac PMMS, October 22, 2026). This is the third North Carolina pass of the year, after June and August, and it re-runs the same inputs at the new rate: 25% down, a 30-year fixed, landlord insurance at 0.68% of value, 8% management, one month of vacancy a year, and county tax rates of 0.80% in Mecklenburg, 0.75% in Wake and 1.14% in Cumberland.
One caution on the inputs: prices are carried from the August pass (Redfin's three-month medians through May 2026 and Zillow's June 30, 2026 value index), because no newer city-level medians for these three markets were published when I checked. Rents come from Zumper and RentCafe 2026 listings. Treat the price column as the thing to refresh with a current comp before you make an offer.
Get this in your inbox every Friday.
One email. The number that matters and what it means for you.
North Carolina cash flow at 7.32% versus 6.67% in August
| Market | Price | Rent | P&I | Tax | Insurance | Full payment | Net cash flow | Coverage |
|---|---|---|---|---|---|---|---|---|
| Charlotte | $435,000 | $2,100 | $2,241 | $290 | $246 | $2,777 | -$1,006 | 0.64 |
| Raleigh | $444,326 | $1,950 | $2,289 | $278 | $252 | $2,819 | -$1,174 | 0.58 |
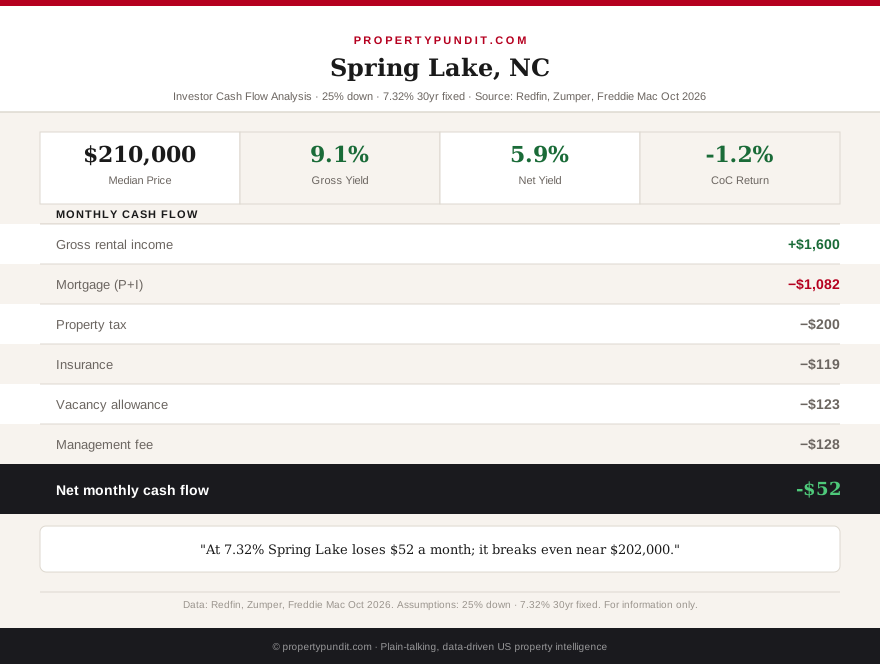
| Spring Lake | $210,000 | $1,600 | $1,082 | $200 | $119 | $1,401 | -$52 | 0.96 |
Net cash flow uses effective rent after 8% management and one month of vacancy ($1,771, $1,645 and $1,349), and coverage is that effective rent divided by the full payment. At August's 6.67% the same three deals read -$864, -$1,029 and +$17. The rate move alone cost Charlotte $143 and Raleigh $145 a month, and Spring Lake $69 on its much smaller loan. If your North Carolina model was built before the fall, it overstates your cash flow by roughly that amount, so rerun it today.
Charlotte and Raleigh: the rent they'd need is a fantasy
Charlotte's full payment of $2,777 needs about $3,293 of gross rent to break even after management and vacancy, 57% above the $2,100 three-bedroom average. Raleigh needs about $3,343 against $1,950, a 71% jump. No Triangle or Queen City submarket is going to deliver that this year, and gross yields of 5.79% and 5.27% show why: tax and insurance alone take $536 and $530 a month before the lender gets a dollar.
The Charlotte price is also the shakiest number here. Redfin's three-month median ran $435,000 through May, but Redfin's January to March average reported by Stacker and WSOC was about $403,000. Use the lower figure and Charlotte still loses $802 a month. The sources disagree by $32,000, and it doesn't rescue the deal either way. If you're eyeing either metro for monthly income, the math points toward leaving it alone until rent or price moves by a third; the case for owning here is appreciation, which you'd be funding out of your own pocket at about $1,000 a month.
Spring Lake: where the $17 went
August's Spring Lake deal was $210,000, $1,600 rent and $17 of monthly profit (see the August pass). The only change is the rate: P&I rose from $1,013 to $1,082, a $69 jump, and the $17 cushion became a $52 loss. Coverage fell from 1.013 to 0.96, below the 1.0 line most DSCR lenders want to see. Our DSCR loan guide covers how lenders count that ratio and what they do when it slips under 1.0.
Four levers pull it back, each tested on its own against the $210,000 base:
| Lever (one at a time) | Change | Monthly cash flow |
|---|---|---|
| Base case | $210,000, 7.32%, $1,600 rent, 25% down | -$52 |
| Negotiate the price | About $202,000 (3.8% lower) | About $0 |
| Rate falls | About 6.85% | About $0 |
| Put more down | 30% down instead of 25% | +$20 |
| Raise the rent | $1,700 instead of $1,600 | +$33 |
The price lever is the only one you control at the closing table. Fayetteville's median sale price was $235,000 in the three months through May, down 2.1% from a year earlier (Redfin), so a 3.8% concession on a Spring Lake house is a reasonable ask, not a stretch. Rents are the least reliable lever: published estimates for what an E-5 with dependents receives in housing allowance at Fort Liberty run from about $1,461 to $1,806 depending on ZIP code and source, so confirm the current figure on the Defense Department's calculator before you assume a tenant can stretch to $1,700. If you're going to chase this market, the first move is a lower price or more cash down, not a hopeful rent bump.
What North Carolina's tax and insurance changes do and don't fix
North Carolina's flat income tax fell to 3.99% for 2026 from 4.5% in 2025, and the state's insurance commissioner settled a requested 68.3% dwelling-insurance increase for roughly 5% a year over two years (North Carolina Department of Insurance, 2026). Both are real, and both are small beside a $69 swing in the mortgage payment. A 5% insurance increase on Spring Lake's $119 adds about $6 a month, and a lower income tax rate only helps when there's profit to tax. Spring Lake has none at 7.32%.
The state's landlord-friendly rules (no rent control, short eviction notice periods) are why investors keep coming back, and they're worth something in a bad month. They're not worth $52 a month. For you, the structural advantages argue for staying alert to North Carolina when rates ease, not for buying at today's 7.32% and hoping the legal climate covers the gap.
The call on North Carolina right now
Frankly, if you need positive monthly income today, skip Charlotte and Raleigh. They lose $1,006 to $1,174 a month, and no reasonable negotiation closes that. In Spring Lake, the math points toward either an offer near $202,000, or 30% down (which turns the deal to +$20), or waiting for a rate near 6.85%. Most people who run these numbers end up in the third camp, because a $20 monthly profit doesn't pay for a single surprise repair. Compare yields across the state's lower-priced counties in our county yield map before you commit to one market, and use today's 7.32% rather than last quarter's rate when you do.
Frequently asked questions
Does North Carolina have positive-cash-flow rentals at 7.32%?
Not at the median in Charlotte or Raleigh, which lose $1,006 and $1,174 a month. Spring Lake near Fort Liberty slipped to -$52 a month at a $210,000 price, and breaks even near $202,000.
Which rate makes Spring Lake break even again?
About 6.85% on a 25%-down, 30-year loan at a $210,000 price with $1,600 rent. At August's 6.67% the same deal made $17 to $18 a month.
Is Charlotte or Raleigh the better rental market?
Charlotte, narrowly: it loses $1,006 a month versus $1,174 in Raleigh because rent runs $150 higher against a similar price. Neither is close to break-even.
How much did the rate increase hurt North Carolina cash flow?
The move from 6.67% in August to 7.32% now cut monthly cash flow by about $143 on Charlotte, $145 on Raleigh and $70 on Spring Lake, whose loan is half the size.