 Property
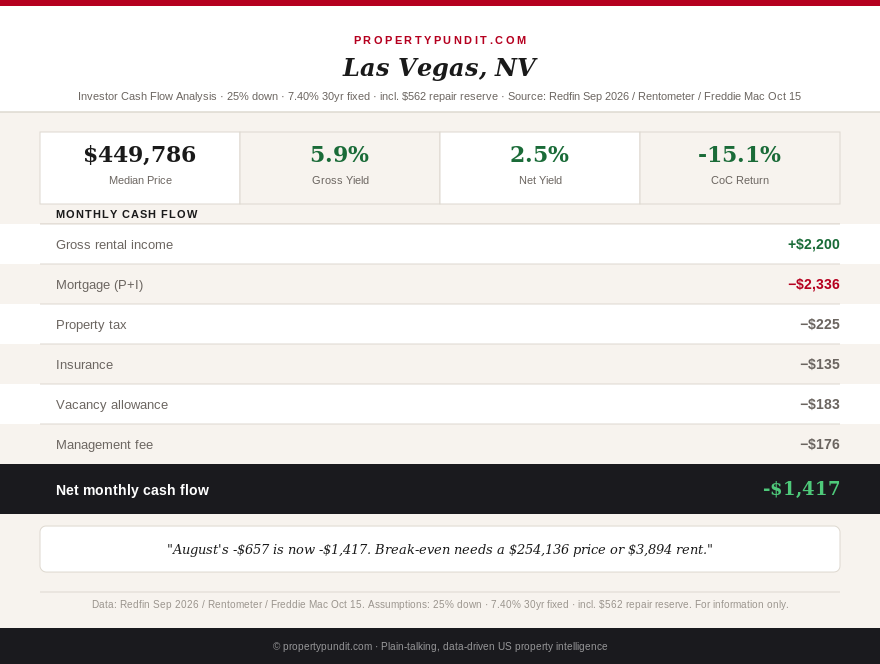
You own a couple of rentals, you've heard Nevada has no state income tax and a property tax rate near 0.60%, and a Las Vegas house is starting to look like the obvious next buy. At the Freddie Mac rate of 7.40% (October 15, 2026), the median Las Vegas house ($449,786, Redfin, September 2026) loses $1,417 a month as a rental on a 25% down payment. In August this site published -$657 for the same market.
The price that works is near $254,000, which is 43% below the median. Henderson, North Las Vegas and Reno all lose more than Las Vegas does, so the gap is a Nevada pattern and no single city's problem. Nevada's tax advantages are real, but they only pay when a property earns something to tax.
This is the third Nevada pass of the year. The method matches the recent state passes: 25% down, a 30-year fixed at 7.40%, the Clark County effective property tax rate, an insurance estimate scaled from a Las Vegas quote, 8% management, one month of vacancy a year and a 1.5% annual maintenance reserve.
Get this in your inbox every Friday.
One email. The number that matters and what it means for you.
Nevada cash flow at 7.40%, market by market
| Market | Price | Rent | Full payment | Net cash flow | August result | Coverage | Break-even rent |
|---|---|---|---|---|---|---|---|
| Las Vegas | $449,786 | $2,200 | $2,695 | -$1,417 | -$657 | 0.82 | $3,894 |
| Henderson | $495,422 | $2,290 | $2,969 | -$1,672 | -$779 | 0.77 | $4,289 |
| North Las Vegas | $422,470 | $1,950 | $2,532 | -$1,428 | -$502 | 0.77 | $3,657 |
| Reno | $577,118 | $2,450 | $3,462 | -$2,134 | -$1,096 | 0.71 | $5,000 |
Prices are Redfin median sale prices: Las Vegas $449,786 (September 2026, up 1.1% year over year), Henderson $495,422 (three months ending August 2026, up 0.1%), North Las Vegas $422,470 (August 2026, up 1.8%) and Reno $577,118 (August 2026, up 4.9%). The Las Vegas rent is a Rentometer three-bedroom house median of about $2,200 (October 2026). The Henderson, North Las Vegas and Reno rents are carried from the August pass and I didn't re-verify them. "Full payment" means principal, interest, property tax and insurance; "coverage" is rent divided by that payment.
Coverage under 1.0 means the rent doesn't cover the mortgage payment, tax and insurance before any operating cost. Many DSCR lenders look for 1.0 or better, so every market in the table would struggle at the underwriting stage as well as in your bank account. For how those loans are underwritten, see the DSCR loan guide.
Why August's -$657 became -$1,417
Two changes did most of the damage, and only one of them is the market. The method change is bookkeeping; the rate change is real money.
| Step | Las Vegas net per month | What changed |
|---|---|---|
| Published August 11 | -$657 | 6.69% rate, $450,000, $2,150 rent, 5% vacancy, no repair reserve |
| Same inputs, today's method | -$1,299 | One month of vacancy plus a $562 monthly maintenance reserve (-$642) |
| Rate rises to 7.40% | -$1,460 | Principal and interest up $161 a month |
| Today's price, rent and insurance | -$1,417 | Rent $2,200 vs $2,150, price $449,786 vs $450,000 (+$43) |
The maintenance reserve ($562 a month on a $449,786 house) is the largest single line. It's money you don't spend every month, but a roof, an air conditioner or a water heater arrives eventually, and a Las Vegas summer is hard on air conditioning. If you refuse to count any reserve, the result is still about -$855 a month, which is worse than August's published figure. That's the rate talking: P&I rose from $2,176 to $2,336 on essentially the same house.
If you underwrote a Las Vegas property in the summer at 6.69% and it looked tolerable, rerun it at 7.40% before you make an offer. A quarter-point of rate on this loan is about $58 a month, and the move since August is 71 basis points.
What the Las Vegas market data says
The Las Vegas Realtors reported a September median single-family price of $470,000, flat against September 2025 and down 1.1% from August. Redfin's $449,786 is lower because it blends condos and townhomes with houses and uses a different window. Both are correct for their own definitions. I use the Redfin figure because it matches the rest of this site's state passes.
The more useful numbers are about pace. The Realtors counted 2,169 sales in September, with single-family sales down 7.4% and condo and townhome sales down 12.6% from a year earlier. Single-family listings without offers rose 6.6% to 7,995, and the sales pace equals about five months of supply, up from roughly four a year ago (Las Vegas Realtors, October 2026). Redfin shows 40.5% of Las Vegas homes with a price drop, up 3.6 points from last year, a median of 55 days on market and a 98.1% sale-to-list ratio.
Cash buyers made up 23.5% of September sales (Las Vegas Realtors), nearly unchanged from last year. Those buyers don't care about the 7.40% rate, which is one reason prices aren't falling faster. If you need a mortgage, you are bidding against people who don't.
Association president George Kypreos said recently rising mortgage rates are playing a bigger role in the market. For a buyer paying 7.40%, five months of supply and a 40.5% price-drop share are negotiating room. Use it on price, because a lower price cuts every line of the payment, not only the principal.
The rent and the price that would work
You can reach break-even from either side, and neither side is close. Holding the price at $449,786, rent would have to reach $3,894 a month. Holding rent at $2,200, the price would have to fall to $254,136.
| Las Vegas rent assumed | Source | Net per month |
|---|---|---|
| $2,150 | August pass (RentCafe, June 2026) | -$1,459 |
| $2,200 | Rentometer three-bedroom house median, October 2026 | -$1,417 |
| $2,309 | Rentometer three-bedroom, all property types, October 2026 | -$1,326 |
| $2,317 | HUD FY2027 three-bedroom fair market rent, effective October 1, 2026 | -$1,319 |
Rent isn't the lever. Moving from the lowest rent to the HUD limit adds only $140 a month, against a $1,417 gap. Reaching $3,894 would take rent 68% above the HUD three-bedroom figure, which no tenant pool in Clark County will pay for a median house. The HUD number comes from the Nevada Real Estate Group rent guide, which is a secondary source, so check the HUD table directly if you plan to rely on it.
A $254,136 Las Vegas house is a condo or a very old, small house in a weaker neighborhood. That's a different asset, with different tenants and higher repair risk, so don't treat the break-even price as a shopping target. Treat it as a measure of how far the market sits from landlord math.
Does appreciation cover the gap?
Not at the current pace. Redfin's Las Vegas median rose 1.1% year over year, which on $449,786 is $4,948 of value. Add $3,171 of principal paid down in year one on a $337,340 loan, and the equity gain is $8,119. The cash drain is $17,004 a year (12 months at -$1,417), of which $6,744 is the maintenance reserve. Even if you treat the reserve as a paper cost, you'd have $10,260 of real cash going out against $8,119 of equity coming in.
To break even on cash plus equity in year one, the price would have to rise about 3.1% ($13,800) in 12 months, including the reserve as a cost. Nevada's appreciation record under limited land supply is the usual argument for buying, but the current trend is 1.1% with sales falling. A thesis that depends on prices re-accelerating in a 7.40% market needs a reason beyond the last decade.
Nevada's tax edge, priced honestly
Nevada has no personal income tax and no state capital gains tax, and Clark County's effective property tax rate runs about 0.60% (carried from the August pass; not a parcel bill). On this house that is $225 a month, against roughly $693 a month on the same price at Texas's 1.85% average rate. That $468 monthly gap is real, and it's why investors compare the states.
The income tax advantage is worth nothing when the property loses money. A loss produces no Nevada income to shelter and no state deduction to claim. The tax edge starts to matter only at prices where the property earns a profit, and the profit has to be large enough to be worth sheltering.
The cap rules deserve a look. Clark County says the tax bill on a non-owner-occupied residence is capped at up to 8% growth a year, and that some rentals that meet HUD-based rent limits qualify for the 3% cap. On this house, if both caps bind each year, the gap is about $634 a year ($53 a month) by year five. Call the Clark County Assessor at (702) 455-3882 to confirm whether a single-family rental qualifies and what to file, because the county's page describes the affidavit process mainly for duplexes and larger buildings.
What this means for you
Skip Las Vegas, Henderson and Reno as cash-flow purchases at 7.40%. If your thesis is appreciation, Las Vegas isn't supplying it right now, and you'd be paying about $17,000 a year to wait. If you already own a Clark County rental, this is the week to rerun your numbers at today's rate and check which tax cap your parcel gets.
If you still want a Nevada position, three moves make it less costly. Negotiate hard on price while 40.5% of listings carry a price drop, because every $10,000 off the price saves about $60 a month across principal, interest, tax and insurance. Ask for a seller credit and put it toward a rate buydown instead of closing costs. And compare with a market where the rent-to-price ratio is higher, such as Nebraska, where a $175,000 Omaha house nets -$7 a month at the same rate.
What I couldn't verify
Several inputs are carried, scaled or dated. The 0.60% Clark County effective tax rate and the 0.64% Reno rate come from the August pass and are county-level averages, not parcel bills. Insurance is scaled from one Insurify Las Vegas figure ($1,440 a year for $300,000 of dwelling coverage, September 30, 2026) and assumes dwelling coverage equals 75% of price; Reno uses Insurify's $1,308 statewide figure. Neither is a landlord policy quote, and landlord coverage usually costs more. The Henderson, North Las Vegas and Reno rents are August carry-forwards, and North Las Vegas's August result used a $390,000 price I estimated, so its jump to -$1,428 partly reflects a corrected price. I didn't find a parcel-level assessor figure or a current Henderson house rent comp.
Frequently asked questions
Is Las Vegas a good place to buy a rental property at 7.40% mortgage rates?
Not for cash flow. At 7.40%, the median Las Vegas house ($449,786) rented at $2,200 loses about $1,417 a month on 25% down after 8% management, one month of vacancy and a 1.5% maintenance reserve. The case for Las Vegas has to rest on appreciation, and Redfin shows only 1.1% year over year.
What rent does a Las Vegas house need to break even at 7.40%?
About $3,894 a month on a $449,786 purchase with 25% down. That is 77% above the $2,200 rent used here and 68% above the $2,317 HUD fair market rent for a three-bedroom in Clark County effective October 1, 2026.
Does Nevada's 3% property tax cap apply to rental houses?
Clark County applies a cap of up to 8% to non-owner-occupied residences and says some rentals that meet HUD-based rent limits can get the 3% cap. On this house the difference is about $53 a month by year five if both caps bind every year, so confirm eligibility with the Assessor before counting on it.
Why did the Las Vegas rental math get worse since August?
The method now includes a 1.5% maintenance reserve and a full month of vacancy (-$642 a month), the rate rose from 6.69% to 7.40% (-$161), and slightly higher rent and a marginally lower price offset $43. August's published figure was -$657; the same market is -$1,417 today.