 Property
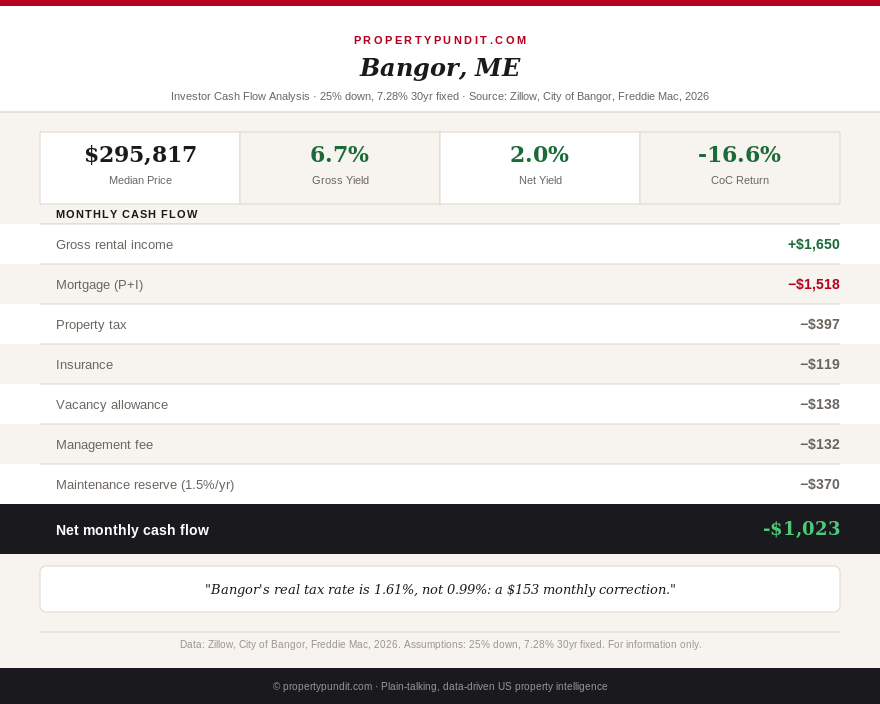
You're about to wire $73,954 as a down payment on a median Bangor house, and the property tax figure in most listing summaries is off by $153 a month. The City of Bangor's FY2026 rate is 17.70 mills on an assessment ratio of about 91%, which works out to an effective 1.61% of market value, not the 0.99% Penobscot County figure I used in July (City of Bangor Assessing Department, FY2026). Corrected, the median Bangor rental loses about $1,023 a month after management, vacancy and maintenance, with a coverage ratio (rent divided by mortgage, tax and insurance) of 0.81.
This is our third pass on Maine, after the June 7 first pass and the July 29 second pass. The benchmark moved from 6.58% to 7.28% (Freddie Mac PMMS, July 23 and October 1, 2026). I underwrote each market with 25% down, an 8% management fee, one month of vacancy a year and a 1.5% annual maintenance reserve, the same method as our other third-pass states, and I re-sourced price, rent, tax and insurance for Portland, Bangor and Lewiston.
Get this in your inbox every Friday.
One email. The number that matters and what it means for you.
Bangor: the tax rate was the error
Start with price, because two sources disagree. Zillow puts Bangor's median sale price at $295,817 as of July 31, 2026, with a typical home value of $288,461, up 1.1% over the year and about 29 days to pending (Zillow, August 2026). Redfin's three-month median for January through March was $268,333, up 1.5% (Redfin via Stacker, 2026). In July I used $315,000, which came from a Redfin window that showed a 16.6% jump. The price has cooled to about $296,000, so I used Zillow's recent sale figure.
Rent is the weaker input. I kept the $1,650 single-family estimate from July, because the only fresh public number is Apartments.com's $1,426 for a 3-bedroom average, up 0.1% year over year (Apartments.com, October 2026), and that figure blends apartments with houses. At $1,426 the monthly loss deepens to about $1,211, so treat $1,650 as the generous case.
The tax correction is the real find. Bangor's FY2026 commitment report shows a rate of $17.70 per $1,000 of net valuation and a median assessment ratio of roughly 91% (City of Bangor Assessing Department, FY2026). Multiply them and you get 1.61% of market value, or $397 a month on a $295,817 house. The 0.99% county figure would have produced $244. What it means for you: never underwrite a Maine house on a county average. Pull the town's mill rate and its assessment ratio, because they differ by town and neither appears in a listing.
| Monthly line item | Portland | Bangor | Lewiston |
|---|---|---|---|
| Median price | $583,376 | $295,817 | $308,833 |
| Down payment (25%) | $145,844 | $73,954 | $77,208 |
| Rent (3-bedroom house) | $2,600 | $1,650 | $1,700 |
| Principal and interest (7.28%) | $2,994 | $1,518 | $1,585 |
| Property tax | $582 (1.20%) | $397 (1.61%) | $438 (about 1.70%) |
| Insurance | $150 | $119 | $99 |
| Management (8%) | $208 | $132 | $136 |
| Vacancy (one month a year) | $217 | $138 | $142 |
| Maintenance reserve (1.5% a year) | $729 | $370 | $386 |
| Net monthly cash flow | -$2,280 | -$1,023 | -$1,085 |
| Coverage ratio (rent / PITIA) | 0.70 | 0.81 | 0.80 |
| Rent needed to break even | $5,325 | $2,873 | $2,997 |
All three fail the 1.0 coverage minimum that DSCR lenders use. Bangor comes closest, but its break-even rent of $2,873 is 74% above the $1,650 rent I assumed. Bangor's value index rose about $3,170 over the past year on a $288,461 typical home, against a carrying loss of about $12,276 over the same twelve months.
Portland: flat prices, $2,280 a month of carry
Portland's numbers are the most stable and the least forgiving. Zillow's typical home value is $559,175, unchanged over the past year, with a median sale price of $583,376 as of July 31 and homes going pending in about 17 days (Zillow, August 2026). That's far below the $650,000 I used in July, which came from a different source (Rental Beast, Q2 2026), so the price drop in this pass is partly a source change and not a market crash. Rent is $2,600 for a house on Zillow, flat year over year, and Zillow labels the rental market "cool" with 245 listings (Zillow, September 6, 2026).
Property tax is the one line that fell. Portland's post-revaluation mill rate is 11.98 (WGME, 2026), about 1.20% of full market value, which is $582 a month on this house. Cut the house price, trim the tax, and ownership costs fall $204 a month versus July. It doesn't matter. The 1.5% reserve alone is $729 a month, more than the rent surplus any plausible Portland buyer could expect, and break-even rent is $5,325. With prices flat, there is no appreciation to offset a $27,360 annual loss. What it means for you: Portland works only as a long-term bet on a rent jump of roughly 105%, or as a home you live in.
Lewiston: the thinnest data in the state
Lewiston is the weakest evidence in this pass. Redfin's three-month median for January through March was $308,833, down 1.4%, and Redfin's July statewide table shows Lewiston prices down 4.0% year over year, one of three cities Redfin flagged for declines, alongside Westbrook at 5.1% and Old Orchard Beach at 3.2% (Redfin, July 2026). Androscoggin County's median held flat at $360,000 for June through August (Maine Association of REALTORS, August 2026), so city and county data don't line up.
Rent is a flagged estimate. I carried the $1,700 single-family figure from July. Apartments.com shows only $944 for a 3-bedroom average, down 6.2% (Apartments.com, October 2026), which is plainly an apartment-dominated figure and not usable for a house. Tax is also uncertain. Lewiston's FY2026 rate is $32.77 per $1,000, up $1.00, but the city assesses below market value, and a 2022 state estimate put its full-value rate near $17 per $1,000 (Sun Journal, 2026). I used about 1.70%, which gives $438 a month and a loss of $1,085. If the true rate were Ownwell's 2.22% Androscoggin County estimate, the tax line would be $571 and the loss about $1,218. Lewiston's revaluation is expected to reset these numbers in 2027, so it's worth waiting for that data before buying.
What moved since July
Statewide, Redfin's July median was $423,476, up 0.7%, with 7,782 homes for sale (up 4.3%), 4.0 months of supply, 50 median days on market and 18.5% of listings with a price drop, up from 14% a year earlier (Redfin, July 2026). The Maine Association of REALTORS reported an August median of $424,550, up 4.31%, on 1,542 closed single-family sales, down 10.09% (Maine Association of REALTORS, August 2026). The two growth rates differ because they cover different months and methods, and neither shows a market in distress or one running away.
For Bangor, the move from a $368 monthly loss in July to $1,023 now is a $655 swing, and almost none of it is the market. The maintenance reserve ($370) and the vacancy allowance ($138), neither of which July's pass included, account for $508, or 78%. The tax correction is $137, or 21%. The rate moved from 6.58% to 7.28%, which alone adds $111 a month on July's loan, but a $19,000 lower price took back $99, leaving a net $12. Most of the change comes from more complete underwriting; the market itself moved little.
Insurance is the line that barely moved. MoneyGeek puts the Maine average at $1,425 a year, or $119 a month, 59% below the national average of $3,467, with Lewiston at $1,187 a year (MoneyGeek, 2026). I used $119 for Bangor and $99 for Lewiston. For Portland I kept $150, above the state average, because a $583,000 house costs more to rebuild. Maine has far fewer catastrophe losses than the Gulf and Plains states we've covered, and that's the one real advantage in this pass. New Orleans, by comparison, runs $1,021 a month for the same coverage line (MoneyGeek, 2025), per our October 5 pass.
Maine rules that change a landlord's math
Portland's rent stabilization ordinance caps annual increases on existing tenants at 100% of CPI, which is 2.2% for 2026, with 90 days' written notice and one increase a year (City of Portland, 2026). New construction after April 2020 and owner-occupied buildings of four units or fewer are exempt. Bangor and Lewiston have no equivalent ordinance as of this pass. At a 2.2% cap, Portland's $2,600 rent would take more than 30 years to reach the $5,325 break-even.
Maine also taxes rental income as ordinary income at 5.8%, 6.75% or 7.15% for single filers, with capital gains taxed at the same rates (Maine Revenue Services, 2026). Owner-occupants can claim a Maine homestead exemption that lowers their taxable value, and landlords can't, so the tax bill on a rental runs higher than the figure a seller quotes. Confirm the exemption amount with the town assessor before you compare any listing's tax history to your own estimate.
What this means for you
If you want cash flow, Maine doesn't offer it at 7.28%. Bangor is the closest at a $1,023 monthly loss and would need rent near $2,873, 74% above what I assumed, to break even. A bigger down payment closes about 30% of that gap: 40% down on the Bangor house cuts principal and interest by about $304 a month, which still leaves a loss near $719. At that point you're paying for appreciation of about 1% a year, and income doesn't enter into it.
If you're considering Maine anyway, three steps matter. Ask for the mill rate and the assessment ratio for the town, not a county average. Get an actual landlord-policy insurance quote before making an offer. And wait for Lewiston's 2027 revaluation data before touching that market. A rate drop to 6% would help, but on Bangor it recovers only about $190 of the $1,023 loss, so don't count on rates alone to rescue the deal.